Boca Raton Car Insurance: Local Requirements, Storm Risks and Seasonal Driving
Understand Boca Raton Car Insurance Right Now
Boca Raton car insurance should reflect how your vehicle actually spends the year, not just where you receive mail. A car driven daily on I-95 needs different coverage decisions than one parked at a seasonal condo from November through April. Before comparing any price or carrier, sort out who uses each vehicle, where it stays overnight and what happens to it during hurricane season.
FloridaAutoInsurance.com is an insurance information and comparison service operated by Drivers Insurance Agency, Inc. This is not a Boca Raton city office, a government agency or a branch of any single insurer. The information below draws on current Florida statutes, Florida Department of Financial Services consumer materials, U.S. Census data and City of Boca Raton resources. Premiums and coverage outcomes always depend on an individual application and specific policy terms.
Start a Boca Raton car insurance quote or call 833-730-3030 to speak with a licensed representative about vehicles based in Boca Raton.
“Boca Raton car insurance” is a Florida auto policy built around where the vehicle actually stays, who drives it during the year and how storm and seasonal risks shape coverage choices. The city’s coastal location and seasonal households make accurate garaging and vehicle-use information especially useful when comparing policies. Car insurance premiums can vary based on traffic density and regional risk factors, so understanding your own household’s situation matters more than reading a list of statewide averages.
Car Insurance in Boca Raton, Not Just “Florida in General”
A Boca Raton zip code is not interchangeable with a generic FL address, and full-coverage costs can vary across the city’s ZIP codes. Local crash patterns on Federal Highway and Glades Road, coastal storm exposure east of US-1 and the garaging address listed on an application can all affect what companies offer. Compare current quotes using your own address and driving record rather than relying on an unsourced city average.
The U.S. Census Bureau QuickFacts page places Boca Raton’s population at 101,582 as of July 1, 2025. That population estimate describes the city; it does not establish an insurance rate or the value of the vehicles in your household.
Rating factors that can matter for insurance in Boca Raton include:
-
Overnight address within the city. West Boca inland vs. east-of-US-1 beachside locations carry different flood and storm surge exposure.
-
Parking arrangement. A ground-level lot, a high-rise garage and a single-family home garage each present different risk profiles for water intrusion and theft.
-
Commute patterns. Daily use on I-95, Palmetto Park Road or Camino Real creates more exposure than occasional local errands.
-
Frequency of use. A year-round commuter car and a seasonal vehicle driven 12 weekends a year need different descriptions on an application.
Gather your exact addresses before requesting a quote so that Boca Raton conditions can be evaluated correctly. If you split time between two homes, explain both locations.
Florida Minimum Coverage and What Boca Raton Drivers Commonly Add
Florida’s basic insurance requirements include Personal Injury Protection and Property Damage Liability. For most private passenger vehicles registered in the state, that means $10,000 in PIP and $10,000 in property damage liability. The Florida Department of Financial Services automobile insurance overview explains these coverages in detail, and the Automobile Insurance Toolkit PDF walks through examples for consumers.
What each required coverage does:
-
PIP covers a portion of medical costs and lost wages for you and certain passengers after a crash, regardless of fault, subject to statutory terms. Initial services and care must be received within 14 days of the accident; that is not a blanket 14-day deadline for the emergency-medical-condition determination. See section 627.736.
-
Property damage liability pays for damage you cause to another person’s property, such as another vehicle, a fence or a building. It does not pay for your own car.
These minimums do not pay to repair or replace the insured driver’s own vehicle after a crash, theft, flood or storm.
Coverages Boca Raton households can review beyond the minimum:
-
Bodily injury liability at limits appropriate to local traffic densities and asset protection needs. Having adequate liability limits is crucial to protect personal assets in the event of a serious accident.
-
Uninsured/underinsured motorist bodily injury coverage. The DFS consumer guide explains stacking and non-stacking options.
-
Collision coverage for crash damage to the insured vehicle regardless of fault.
-
Comprehensive coverage for non-collision risks such as windstorm, flooding, fire, theft and falling objects, as identified in state consumer materials. Comprehensive coverage pays for damage from non-collision events. Florida law mandates that comprehensive deductibles are waived for damaged windshield repairs.
“Full coverage” is not a legal term. Boca Raton drivers should ask for an itemized list of selected coverages, limits and deductibles rather than accepting a label.
Seasonal and Part-Time Boca Raton Drivers
Snowbirds and part-time residents who leave a car at a Boca Raton condo while spending months in another state face specific Florida rules that go beyond typical policy questions.
Section 627.733(2), Florida Statutes, requires that a nonresident vehicle physically present in Florida for more than 90 days within the previous 365-day period must maintain the required security while it remains in the state. The statute applies whether the vehicle is operated or not. Property damage responsibility requirements also appear in section 324.022.
Two calendar illustrations (these are explanatory, not legal rulings):
-
A vehicle spends 60 days in Boca Raton during winter and 40 days in the fall within the same rolling 365-day window. That is 100 days of physical presence, triggering the requirement even if the owner drove it on only a handful of those days.
-
A couple stores a car in a Boca Raton garage for a 59-day winter stay and returns for two weeks in October (14 days) and three weeks in December (21 days). That totals 94 days; the requirement would apply.
The key is days the vehicle is in Florida, not days behind the wheel. When speaking with an agent or insurer, explain:
-
Where each vehicle spends the off-season (Boca Raton garage, storage facility, another state)
-
Who might check on or move the car while you are away (neighbor, property manager, family member)
-
Whether the vehicle keeps a Florida registration while stored
Do not cancel legally required insurance without understanding registration consequences. Cancelling coverage while maintaining a Florida registration can create legal exposure and potential registration suspension.
Hurricanes, Heavy Rain and Boca Raton Vehicle Protection
Boca Raton faces severe weather, including tropical storms and heavy localized flooding. Many parcels in the city lie in FEMA-designated Special Flood Hazard Areas, including zones AE and VE along the shoreline and Intracoastal areas. The city adopted updated FEMA Flood Insurance Rate Maps on December 20, 2024, which may have reclassified some properties and changed base flood elevations. You can check your flood zone through the City of Boca Raton’s flood zone lookup page.
Atlantic hurricane season runs June 1 through November 30. The City of Boca Raton hurricane information page outlines threats including storm surge, inland flooding, heavy rain, high winds and tornadoes spawned by hurricanes. This article is not an evacuation notice; official city and Palm Beach County alerts control emergency actions.
Pre-season planning for your vehicles:
-
Decide which car the household would take if evacuating and confirm who has keys and access.
-
Check condominium, HOA or garage rules about moving cars from lower parking levels before storms.
-
Verify where spare or seasonal vehicles would be parked relative to expected storm surge or drainage patterns.
Connect that plan to coverage:
-
Comprehensive is the coverage commonly associated with windstorm, flooding, falling debris and theft, subject to policy terms, exclusions and deductibles.
-
Some households carry comprehensive only on financed vehicles. If a second car sits in an exposed parking area near the coast, revisit that decision before June.
-
Each damaged vehicle usually triggers its own deductible. Two cars in the same storm means two deductibles.
-
Ask your insurer about any restrictions on binding or changing coverage when a named storm is approaching Florida. Changes requested after a loss cannot insure earlier damage.
Building a Boca Raton Policy Around Your Household
Accurate driver and vehicle information matters more than assumptions about a “Boca Raton average.” Gather these facts before requesting quotes:
-
Vehicle identification number (VIN) for each car and current odometer reading
-
Exact overnight address where each vehicle is kept (west Boca townhouse vs. beachside condo, for example)
-
Names and birthdates of all household members who may drive, including college students who return on breaks; drivers under 25 often pay higher rates for car insurance
-
Approximate annual mileage and primary use (daily commute, seasonal use, ride-share work if permitted, occasional errands)
-
Loan or lease information and any lender coverage requirements or maximum deductibles
-
Existing policy declarations page to compare current limits and coverages
A shared family car used by a Boca Raton student, a commuter and a seasonal visitor requires discussion about who is the principal driver and how use is described. The insurer needs that detail, not a simplified answer.
Ask how to report mid-term changes such as:
-
A vehicle moved to a college campus in another Florida city
-
Household members starting delivery or app-based driving
-
A car being kept longer in Boca Raton while the owner stays in another state
Deductibles and What You Can Actually Afford in Boca Raton
A deductible is the amount you pay before collision or comprehensive coverage contributes to a covered loss. Choosing a higher deductible can lower your monthly premium but increases out-of-pocket costs if you file a claim. Common deductible options in Florida include $250, $500 and $1,000.
Consider a hypothetical covered repair costing $3,200:
|
Deductible |
Insurer pays (simplified) |
You pay out of pocket |
|---|---|---|
|
$500 |
$2,700 |
$500 |
|
$1,000 |
$2,200 |
$1,000 |
The difference: choosing the higher deductible shifts another $500 of potential expense to the household in a claim. This is an illustration, not a repair estimate or promise of payment.
Before selecting a higher deductible to save money on premium:
-
Ask the insurer for the actual premium difference so you can measure the trade-off.
-
Consider that two Boca Raton cars damaged in the same storm or parking lot event would trigger separate deductibles. If both carry a $1,000 deductible, the household faces $2,000 out of pocket before any coverage applies.
-
Review the deductible ceiling in your own loan or lease agreement before choosing an amount.
Transportation Planning While Your Car Is in the Shop
Even with a second car, Boca Raton households can face transportation gaps if both vehicles are unavailable after a storm or multi-vehicle crash. Repair shops in South Florida can be backlogged for weeks after a major weather event.
Questions to ask about rental reimbursement coverage:
-
Does the policy include rental reimbursement or “loss of use” coverage?
-
What types of claims trigger this benefit (covered collision or comprehensive losses, for example)?
-
What is the daily dollar limit and total maximum benefit, and are there time limits?
-
Must the insured pay the rental company first and then seek reimbursement, or does the insurer have direct-pay arrangements?
Rental reimbursement on an auto policy usually does not cover general evacuation travel, hotels or every form of transportation during a storm. Keep receipts and discuss any extensions with the insurer before reaching coverage limits.
Practical steps for Boca Raton residents:
-
Identify nearby rental agencies or car-share options before a loss occurs.
-
Consider public transit, carpooling or remote work arrangements if repairs take longer than expected.
How to Compare Boca Raton Car Insurance Quotes Effectively
Comparing offers only produces useful data when the facts and coverages match across companies. It is advisable to compare at least three quotes from different insurers before choosing a policy.
-
Match the facts. Confirm the same drivers, vehicles, Boca Raton overnight addresses and seasonal dates are used in every quote.
-
Match the coverage. Quote the same liability limits, PIP, optional bodily injury, UM, then layer collision and comprehensive options consistently.
-
Match the deductibles. Keep collision and comprehensive deductibles identical when comparing premiums so the difference reflects the insurer, not a higher out-of-pocket cost.
-
Match the payment terms. Ask for the total cost over the policy term, including installment, billing or service fees.
-
Confirm eligibility details. Request information about available discounts without assuming a particular percentage or that every household will qualify. Many insurance carriers offer telematics programs that track driving behavior for possible discounts.
-
Coordinate the switch. Confirm written evidence of new coverage is in place before cancelling an existing policy. Save digital or paper copies.
Who Boca Raton-Focused Auto Guidance Helps Most
This Boca Raton approach applies to several driver situations, each with distinct needs:
-
Year-round commuters who drive daily on I-95, Glades Road or Palmetto Park Road and face traffic density risks every trip
-
Seasonal residents who keep one vehicle at a Boca Raton condo and another at an out-of-state home, who should check the more-than-90-day physical-presence rule
-
Families with teen or college drivers who split time between a Boca Raton address and another Florida city or campus
-
Retirees who drive infrequently but need to understand storm risks, storage arrangements and minimum legal requirements; about 24.6% of Boca Raton residents are 65 or older
This article is not limited to a single insurer. FloridaAutoInsurance.com is an information and comparison resource for Florida drivers seeking to understand their options across multiple companies.
What Boca Raton Drivers Can Expect for Car Insurance Rates (Without Quoting Specific Prices)
Your current quote should identify the policy term, coverages, limits, deductibles and total premium. A price without those details cannot establish value.
Florida’s Department of Financial Services recommends checking an insurer’s license and financial ratings before buying. Ask how the insurer uses garaging location and driving history in your quote.
Treat online cheapest-company lists as dated comparisons with specific assumptions. The best price for your household requires a current quote.
How to Start Your Boca Raton Auto Quote Today
Have the following information ready to start:
-
Visit the Boca Raton quote page to provide vehicle, driver and address details online.
-
Or call 833-730-3030 to speak with a licensed representative of Drivers Insurance Agency, Inc. about Boca Raton-based vehicles.
-
Have your VIN, driver’s license numbers, current mileage and an existing policy declarations page ready to make the process smoother.
-
Ask the representative to explain each recommended coverage and deductible in plain language before you decide.
Starting a quote does not obligate you to purchase a policy. No single insurer is guaranteed to be the lowest for every Boca Raton driver, and the deal that works for your neighbor’s household may not match your own.
Questions Boca Raton Drivers Ask
Can I use my out-of-state address for a car that stays in Boca Raton?
The insurer needs to know where the vehicle is actually kept overnight most of the year, not the mailing address used on other accounts. Under Florida Statute 627.733(2), a vehicle physically present in Florida for more than 90 days within the previous 365-day period must maintain required security. Choosing an address solely to obtain a lower price can make the application inaccurate and may affect coverage if a claim is filed. Describe your residency pattern, vehicle location and travel schedule honestly so the insurance agent can identify the proper state requirements and policy structure.
Does the Florida minimum cover hurricane or flood damage to my own car?
No. The basic PIP and property damage liability minimums do not create a fund to repair or replace the insured’s own vehicle after flood, storm surge or wind damage. Comprehensive coverage, if purchased, is the part of an auto policy that addresses non-collision perils such as windstorm and flood, subject to specific terms, deductibles and exclusions. Review your declarations page or contact your insurer to confirm whether comprehensive is in place on each Boca Raton vehicle before storm season.
What if my college student takes a car from Boca Raton to another Florida city?
Insurers need to know where the vehicle will be garaged and how it will be used at school, especially if it leaves Boca Raton for Gainesville, Tallahassee or Orlando. Contact the insurer before the move to discuss the new garaging ZIP code, approximate mileage, whether the student is still considered part of the Boca Raton household for rating purposes and any impact on discounts or eligibility. Updating the policy is more reliable than assuming last year’s household description still applies.
Can I pause my Boca Raton coverage when I leave for the summer?
Cancelling or reducing coverage on a Florida-registered vehicle can affect both legal compliance and the vehicle’s registration status. A “storage” or reduced-use description is different from cancelling required coverage. Confirm in writing what is allowed by your insurer and by state rules before making changes. Ask what coverage would apply while the car sits unused in Boca Raton.
How can I tell if an online Boca Raton offer is trustworthy?
Look for clear identification of the agency or service, including Florida licensing information. Verify that the site provides disclosures specifying whether it is an information and comparison service or a government office. Be cautious of websites promising specific savings percentages or guaranteed “cheapest” offers without reviewing personal details. Confirm that any agent or service can provide policy terms in writing, with time to review coverage details and ask questions before buying.
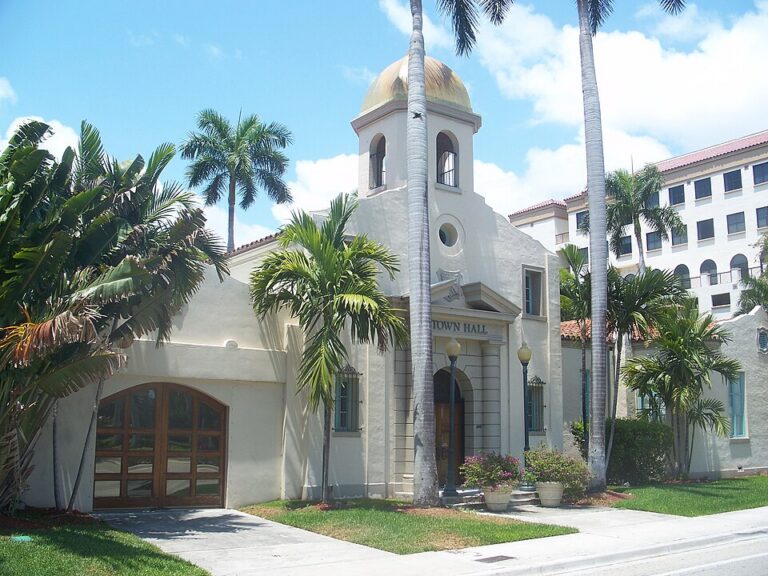
Boca Raton Image, City Resources and Further Reading
For more Florida coverage explanations and city-specific pages, explore FloridaAutoInsurance.com’s resources below.
-
Florida coverage guide for explanations of each coverage type
-
Florida city directory to explore other communities
-
Boca Raton quote page for readers ready to review their own households
Source check: statutes, Florida DFS materials, Census data and Boca Raton city links were reviewed as of October 26, 2026. Requirements and insurer offerings can change; verify details at the time of purchase.